
Acquisition & Divestment
Asset Planning & Management
Business Strategy & Transformation
Data, Analytics & AI
Enterprise Technology
Operational Technology Services
Operational Technology Services


Trending

What We Do
Industries
Solutions
After MSAT-II regulations, most refiners chose to install a solution that included two main steps:
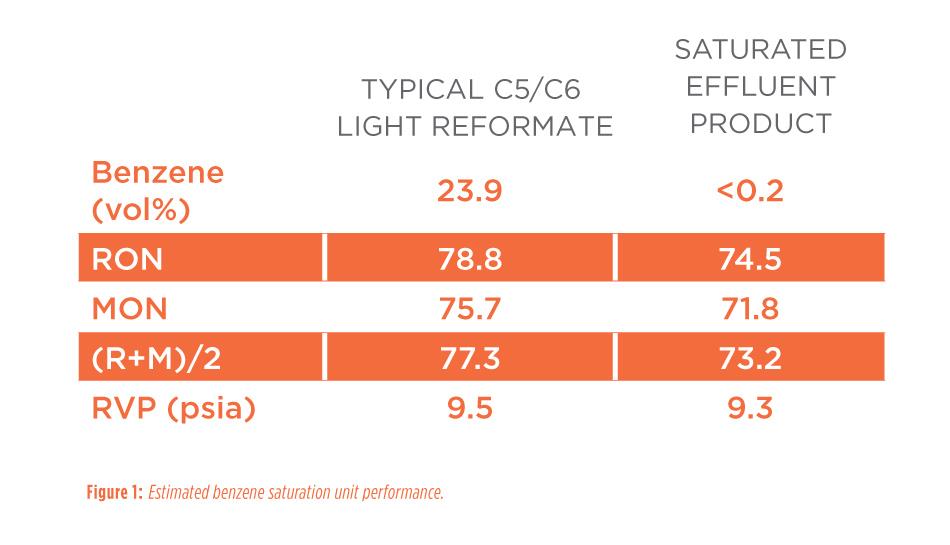
The saturation of benzene is a destruction of octane and a large consumer of hydrogen, which leads to an increase in operating costs and reduction in refinery margin, as shown in Figure 1. Furthermore, if the refinery implements the two steps outlined above and feeds the resultant high-precursor light straight-run naphtha and the low-benzene reformate into an isomerization unit to retrieve lost octane, the resultant feedstock can have a detrimental impact on the overall approach to equilibrium in the isomerization unit due to a high X-factor (defined as feedstock content of C6 naphthenes, benzene and C7+). This further reduces potential octane gain across the downstream unit.
Several major changes have occurred to the market since the introduction of the MSAT-II regulations. Changes — such as additional gasoline regulations (Tier III) — have impacted both the benzene supply in the U.S. and octane demand in gasoline pools by affecting the refinery octane balance and creating a shale gas revolution in U.S. petrochemical production. This, in turn, has affected the steam cracker feed slate and the discovery and subsequent processing of shale condensate.
Octane is in high demand due to three primary contributing factors:
To combat an overall loss in octane, refiners can increase reforming severity. However, this generally will produce more benzene in the light reformate, potentially compounding the existing problems for many refiners.
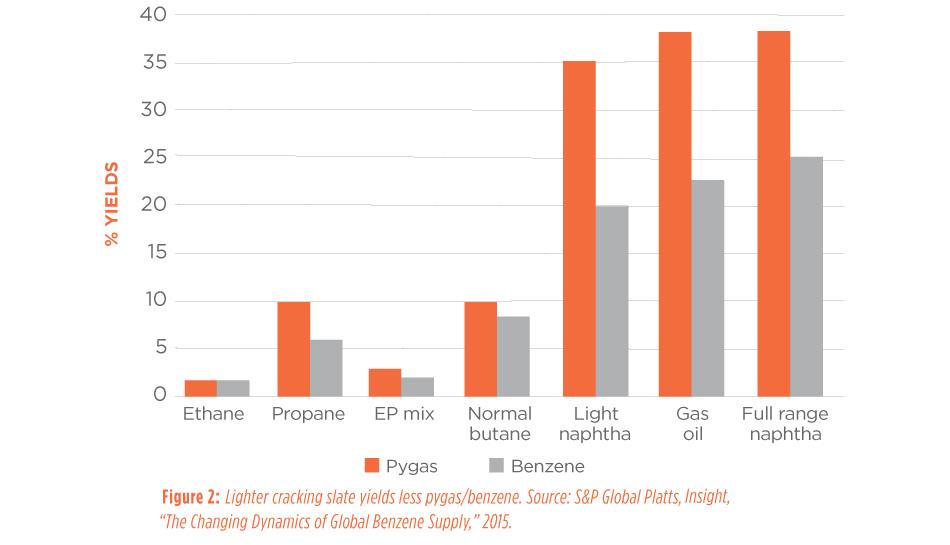
The U.S. steam cracking industry previously processed a mix of natural gas liquids (NGLs), naphthas and gasoils. However, market shift over the last five years, according to S&P Global Platts, has increased the ethane portion of the U.S. cracking slate to more than 90% of the feedstock as the industry moves away from naphtha and gasoil cracking. This shift results in a significant reduction in benzene and pyrolysis gasoline (pygas) yield from steam cracking, evidenced by Figure 2. This shift has affected both the benzene and octane supply markets, as less benzene is being produced from steam cracking, and less pygas — a high-octane gasoline blending component due to the high aromatics content — is available for blending.
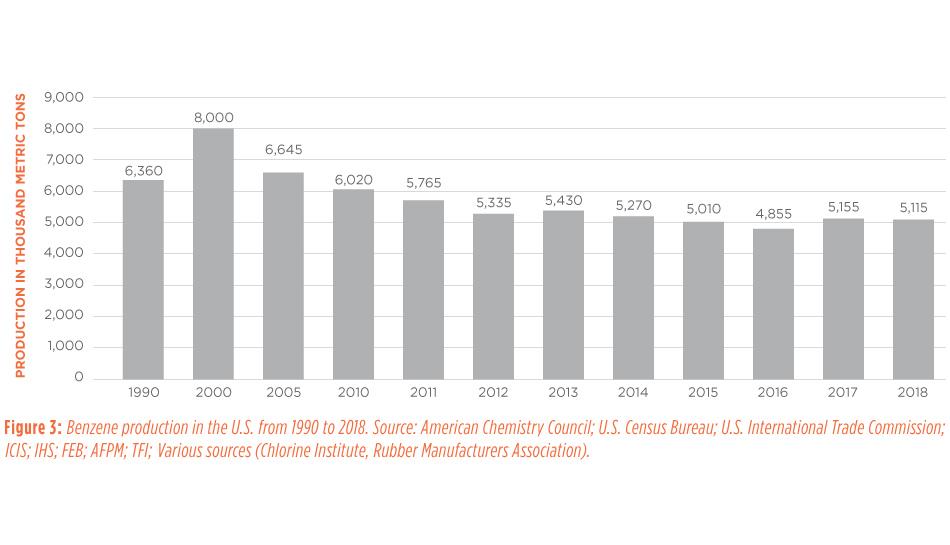
The U.S. is producing only 5.1 million metric tons of benzene per year, as shown in Figure 3. This is down from 8 million metric tons per year in 2000, meaning the U.S. is now importing much of this differential, approximately 1.7 million metric tons per year in 2018.
During MSAT-II compliance studies, other technologies were likely considered before a saturation option was selected. In today’s market, there are commercially proven technologies that can assist a refiner in meeting MSAT-II requirements.
Benzene alkylation technology itself is not new; this technology has been utilized for many years to produce cumene. However, this technology has recently been commercialized to process a benzene-rich feedstock such as C5/C6 range light reformate into a stream containing corresponding branched aromatic analogues of benzene by reacting with ethylene or propylene.
In other words, a light reformate stream can be fed to a benzene alkylation unit directly, converting the benzene into other molecules that satisfy the MSAT-II regulation while also increasing the octane and reducing the Reid vapor pressure (RVP) of the resultant stream. As noted, a light-olefin stream is required as a reactant; however, these streams are bountiful and relatively inexpensive in certain parts of the U.S. today, especially the U.S. Gulf Coast.
Another advantage of this process is it may be possible to retrofit an existing benzene saturation unit into a benzene alkylation unit with modifications.
It should be noted that the endpoint of the gasoline component will be much higher than the feedstock due to heavy aromatics production. Refiners must be careful to see that the resultant stream will continue to meet specifications when blended into the larger refinery pool.
Dividing wall columns (DWC) combine two or more distillation columns within a single shell to enable three or more products to be separated from a feed stream. Applied to a reformate stream, a DWC can produce a benzene-rich stream and an MSAT-II-compliant benzene-lean stream intended for direct gasoline blending. The benzene-rich stream can then be processed separately, reducing overall operating costs. This technology boosts savings in both energy consumption and total distillation column area as compared to separate columns.
There are multiple commercial examples of DWC technology being employed as part of an overall MSAT-II compliance solution.
In the right circumstances, benzene extraction via extractive distillation may be a profitable option for refiners if there is an adequate volume of benzene-rich streams available to justify investment. The U.S. is currently importing significant volumes of benzene, as benzene production from naphtha cracking diminished significantly between 2015 and 2020. Furthermore, refiners may be able to sell a tightly fractionated benzene-rich stream from reformate to petrochemical producers who have spare extraction capacity available today.
In the changing U.S. gasoline and benzene market, decisions made by refiners in 2007 may no longer be optimal in helping a refinery meet today’s demand for premium gasoline and new goals for lower operational costs. Since that time, new technologies in benzene conversion have made it possible to create more cost-effective processes. By refreshing MSAT‑II approaches, refiners can now profit from the investment made in 2007, converting their regulatory projects to an improvement program that will produce profits today and in the future.


